—Josh Allen, B1Daily
Insurance rarely gets discussed as a tool of economic power.
Most people think about it when the bill arrives, when they buy a car, when a mortgage company demands homeowners coverage, or when somebody starts talking about life insurance at the least exciting dinner table imaginable.
But insurance is enormous.
Premiums become capital. Insurance companies employ agents, underwriters, adjusters, executives and financial professionals. They purchase assets, invest money, insure businesses and help families transfer wealth from one generation to another.
For Black Americans, that makes the question of who participates in the insurance industry much bigger than simply finding the cheapest monthly premium.
Supporting Black-owned insurers, Black-owned insurance agencies and Black insurance professionals can help preserve something Black communities once built out of necessity: financial institutions capable of protecting Black families when much of corporate America wouldn’t.
Black Insurers Were Born Because the Mainstream Market Failed Black People
Black insurance institutions didn’t emerge because somebody spotted a cute entrepreneurial niche.

They emerged partly because discrimination created one.
The National Association of Insurance Commissioners has documented a long history of racial discrimination within insurance. Regulators were examining abusive insurance practices targeting Black Americans as early as 1912, including organizations selling Black customers high-premium, low-value policies. Later regulatory debates addressed race-based life-insurance premiums, redlining and unequal insurance availability.
Black entrepreneurs responded by building institutions of their own.
North Carolina Mutual grew out of Durham at the end of the nineteenth century. Atlanta Life followed in the early twentieth century. By 1920, six Black-owned legal-reserve insurance companies operated in the United States, increasing to 15 by 1930.
These weren’t merely companies selling policies.
They became pillars of Black economic infrastructure.
Insurance Premiums Become Economic Power
Here’s what makes insurance different from buying a shirt or eating at a restaurant.
An insurance company collects premiums today while preparing to pay claims tomorrow.
That creates pools of capital.
Historically, Black insurers invested some of that capital into mortgages at a time when discrimination made conventional financing extraordinarily difficult for Black families.
Research published in Business History Review found that Black life insurers became important sources of mortgage financing before 1964. African American insurance companies expanded their mortgage investments during the 1920s, helping provide financing in a market where Black borrowers faced significant discrimination.
That created a remarkable economic loop.
Black families bought insurance.
Black institutions accumulated capital.
That capital could finance Black property ownership.
Homeownership created family wealth.
That is what economic infrastructure looks like.
Black Insurance Created Black Professional Jobs
There was another benefit.
Insurance created careers.

Agents needed to sell policies. Underwriters evaluated risk. Claims required adjusters. Companies needed accountants, managers, executives and attorneys.
At a time when corporate America routinely excluded Black professionals from desirable positions, Black financial institutions created their own ladders into the middle class.
That issue hasn’t completely disappeared.
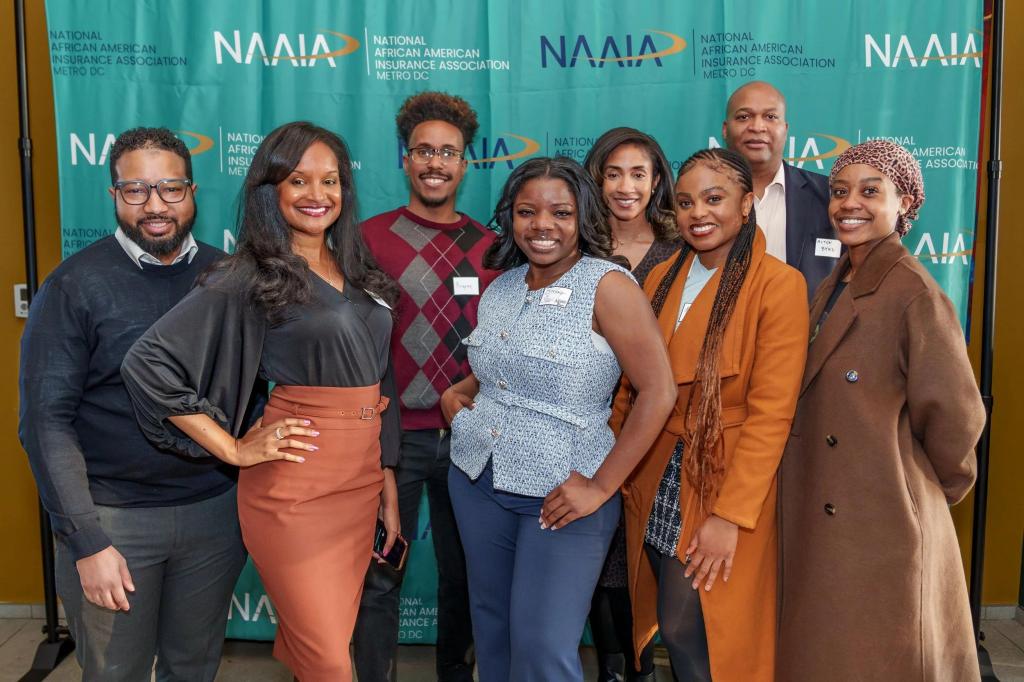
The National African American Insurance Association, founded in 1997, says it now has more than 3,500 members and 33 chapters and remains focused on increasing opportunities for Black professionals throughout insurance.
Its existence tells us something important.
Representation isn’t merely about who appears in an advertisement.
It’s about who becomes an agent.
Who owns the agency.
Who becomes an underwriter.
Who manages billions in risk.
Who reaches the executive suite.
And ultimately, who owns the institution.
Don’t Confuse a Black Agent With a Black-Owned Insurance Company
This distinction is especially important today.
A Black insurance agent selling policies for a giant national carrier is not necessarily operating a Black-owned insurance company.
Likewise, an insurance brokerage, independent agency and insurance carrier aren’t interchangeable.
A carrier actually underwrites insurance risk.
An independent agency or brokerage may be Black-owned while selling policies issued by numerous larger carriers.
Both can be worth supporting, but consumers should understand where their money ultimately goes.
Ask who owns the agency.
Ask which company actually underwrites the policy.
Ask who handles claims.
Ask whether the business is independently owned or simply a local office operating under a national corporation.
Economic empowerment works better when consumers know exactly what they’re supporting.
Supporting Black Professionals Can Multiply Opportunity
There is also a practical reason to seek out Black insurance professionals.
Insurance is complicated.
A good agent doesn’t merely sell you a policy. A good agent explains what happens when your basement floods, somebody crashes into your vehicle, your business burns down, or a family breadwinner dies unexpectedly.
Those relationships can introduce consumers to products they might otherwise overlook, including life insurance, disability coverage, business insurance, umbrella liability and other forms of financial protection.
The goal shouldn’t be racial matching for its own sake.
The goal is expanding a professional ecosystem where Black agents can build books of business, establish agencies, hire employees and eventually create larger financial institutions.
NAAIA was founded specifically because its founder saw insufficient professional connectivity and representation for Black people within insurance. Its programs now emphasize mentorship, education, networking and leadership development.
Customers can become part of that ecosystem.
Black Businesses Need Insurance Too
Supporting Black insurers isn’t only about personal auto and life policies.
Black-owned businesses need commercial insurance.
Restaurants need liability coverage.
Contractors need general liability and workers’ compensation.
Landlords need property coverage.
Trucking companies need commercial auto insurance.
Professional firms need errors-and-omissions coverage.
Cybersecurity increasingly requires cyber insurance.
As more Black Americans pursue entrepreneurship, insurance becomes part of the infrastructure necessary to protect those businesses from catastrophic losses.
One uninsured fire, lawsuit or accident can erase years of work.
A healthy Black business ecosystem therefore needs more than Black restaurants, clothing brands and beauty companies.
It needs accountants.
Banks.
Lawyers.
Investment professionals.
And insurers.
The glamorous businesses get Instagram posts.
The boring businesses build infrastructure.
Insurance is gloriously boring infrastructure.
But Supporting Black Doesn’t Mean Buying a Bad Policy
There should be one enormous qualification to all of this.
Never buy inadequate or wildly overpriced insurance simply because the seller is Black.
Supporting Black businesses doesn’t require abandoning consumer common sense.
Insurance exists to transfer risk. If the company can’t reliably pay claims, the symbolism becomes worthless very quickly.
Consumers should compare premiums, deductibles, exclusions, coverage limits, complaint histories and financial-strength ratings.
Check whether the insurer and agent are properly licensed in your state.
Understand precisely which carrier is underwriting the policy.
Compare several quotes.
Read the exclusions.
Ask what isn’t covered.
The best outcome isn’t charity.
It’s competitive Black-owned businesses winning customers because they provide valuable products and strong service.
That creates sustainable institutions rather than businesses dependent upon guilt-driven purchasing.
History Shows What Happens When Black Institutions Become Powerful
At its height, Black insurance represented something bigger than financial protection.
It demonstrated that Black Americans could pool relatively modest individual payments into institutions controlling substantial capital.
That was particularly significant during segregation.
The industry became developed enough that representatives of Black-owned insurance companies established the National Negro Insurance Association in Durham in 1921.
Black insurance companies grew rapidly during the prosperous 1920s, even though the overall amount of insurance they controlled remained much smaller than that held by white-owned companies insuring Black customers.
That history contains a lesson that remains relevant.
Consumer spending is temporary.
Ownership compounds.
Selling somebody a hamburger creates a transaction.
Owning financial institutions creates capital.
Black Economic Power Needs Financial Institutions
There is nothing wrong with celebrating Black-owned consumer brands.
But genuine economic power requires institutions operating deeper inside the economy.
Banks allocate capital.
Investment firms allocate capital.
Credit unions allocate capital.
Insurance companies accumulate and invest capital while protecting households and businesses against risk.
Those are considerably different functions from ordinary retail consumption.
Supporting Black participation in insurance therefore shouldn’t be treated as another generic “buy Black” slogan.
It should be understood as part of building financial capacity.
The objective isn’t to create an economy isolated by race.
It is to make certain Black Americans aren’t permanently restricted to being customers of financial institutions other people own.
Insure the Community, Build the Institution
A century ago, Black insurance entrepreneurs looked at an industry that frequently discriminated against Black Americans and decided to build alternatives.
Those companies sold policies.
But they also created jobs.
They trained professionals.
They accumulated capital.
They invested in property.
They helped finance homes.
And they demonstrated what could happen when Black consumer dollars were connected to Black institutional ownership.
That history deserves another look today.
When competitive Black-owned agencies, brokers or insurers are available, consumers should at least give them the opportunity to compete for their business.
Get the quote.
Compare the coverage.
Research the company.
Ask who owns it.
And if the policy provides the protection you need at a competitive price, consider where your premium dollars are going.
Because insurance isn’t merely about protecting what somebody already owns.
At its best, it can help communities build enough financial infrastructure to own considerably more.
—Josh Allen, B1Daily
 B1Daily

Leave a comment