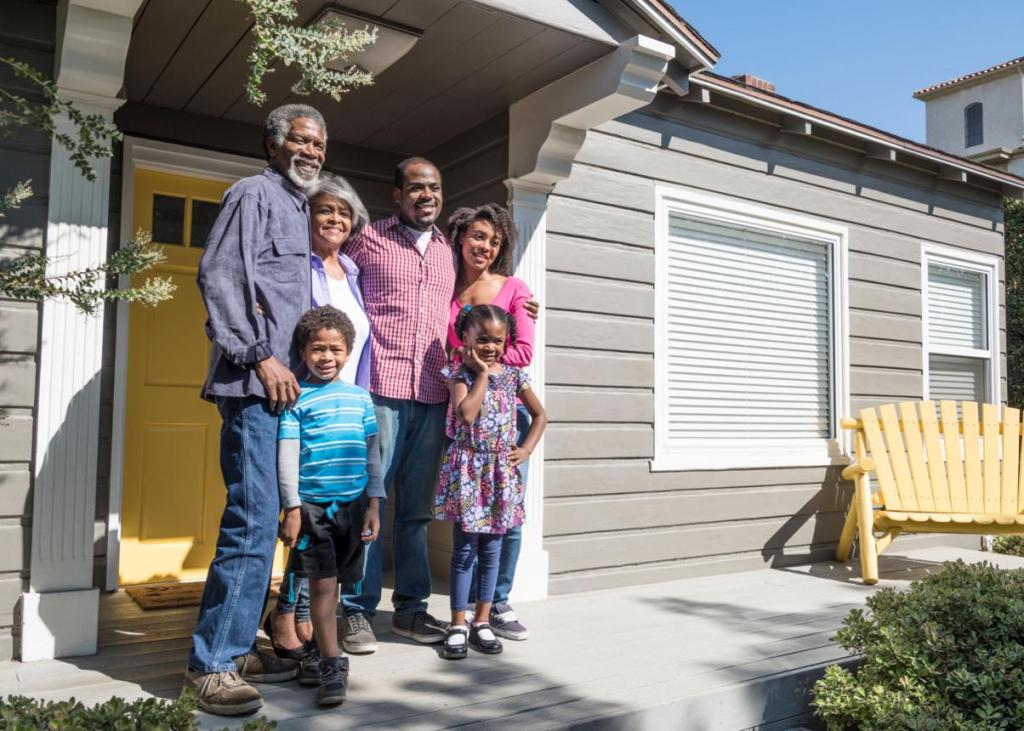
—Michael Lyles, B1Daily
America is witnessing one of the largest intergenerational wealth transfers in its history. Baby boomers are aging, estates are changing hands, and trillions of dollars in accumulated assets are expected to pass to younger generations.
But the financial future awaiting those generations looks radically different depending on whether their parents owned property.
For children of homeowners, inheritance may mean receiving a house, selling inherited property, or using family wealth to purchase a home of their own.
For children of renters, there may be no comparable asset waiting.
And as housing prices continue to challenge first-time buyers, that difference threatens to become one of America’s defining economic divisions.
One Family Inherits Equity. Another Inherits the Rent.
Consider two families that spent 30 years living in the same city.
One family purchased a modest home, gradually paid down its mortgage, and benefited from rising property values.
The other rented throughout those same decades, paying monthly housing costs without acquiring ownership of the property.
Both families may have worked equally hard, raised children, and contributed to their communities.
Yet their children could begin adulthood in dramatically different financial circumstances.
The homeowner’s children might inherit hundreds of thousands of dollars in equity, depending on the property’s value and remaining debt.
The renter’s children may receive little or no housing wealth.
This does not mean every homeowner leaves an inheritance or that renters cannot accumulate wealth through other investments.
But it illustrates how property ownership can create financial advantages that survive long after the original homeowner dies.
The Numbers Reveal an Emerging Divide
According to the Federal Reserve’s October 2026 Survey of Consumer Finances, the median American family’s net worth reached approximately $215,900 in 2025.
Among homeowners, median net housing wealth reached $230,000.
That equity represents a potentially significant financial resource that can be transferred to children.
Research from the Urban Institute warns that the coming wealth transfer may actually widen existing racial and economic inequalities.
Its findings indicate that homeowners are more likely than renters to expect to leave substantial inheritances.
Meanwhile, children from renter households are less likely to anticipate receiving inherited wealth.
A 2025 Census Bureau working paper examining more than 3.4 million families also found that housing wealth persists strongly across generations.
In other words, property ownership can help determine which families remain economically advantaged long after the original purchase.
Black Americans Face a Particularly Dangerous Wealth Divide
The implications for Black Americans are enormous.
Federal Reserve research published in May 2026 found that approximately 44% of Black adults owned their homes, compared with 72% of White adults.
That disparity reflects a long history of discriminatory lending, residential segregation, unequal access to mortgages, and barriers to accumulating family wealth.
For descendants of American slavery, the consequences of historical property exclusion can continue through successive generations.
Families prevented from purchasing homes decades earlier often missed opportunities to accumulate equity and pass valuable assets to their children.
Their descendants may now confront a housing market where inherited financial assistance increasingly influences who can afford to buy.
The Urban Institute has specifically warned that the Great Wealth Transfer could widen not only the Black–White wealth gap but also the economic divide between Black homeowners and Black renters.
The next major wealth divide may emerge within Black America itself, separating families with inherited property from those without it.
The Bank of Mom and Dad Is Becoming a Financial Institution
Inherited houses are only part of the equation.
Parents who own valuable property may be able to help their children purchase homes before an inheritance occurs.
They might provide down-payment assistance, help cover closing costs, or offer financial support during emergencies.
A 2025 Federal Reserve research paper estimated that parental transfers accounted for 13 percentage points of the homeownership rate among young households in its economic model.
This highlights an increasingly important reality: purchasing a home may depend not only on what young adults earn but also on what their parents already possess.
Two workers with identical salaries and credit scores can face completely different financial circumstances when one receives family assistance and the other must save independently.
America likes to celebrate individual achievement.
Its housing market increasingly rewards inherited advantage.
Rising Home Prices Could Make the Divide Permanent
The danger becomes more pronounced when housing prices rise faster than incomes.
Children who inherit property may benefit from appreciation without having to purchase an equivalent asset at today’s market prices.
Meanwhile, renters’ children must contend with down payments, mortgage rates, closing costs, and competition for limited affordable housing.
If they cannot purchase property, they may continue renting while homeowners accumulate additional equity.
That creates a potential cycle in which property-owning families pass advantages to their descendants, while families without property struggle to enter the market.
Over time, the divide can affect retirement security, educational opportunities, business formation, and the ability to withstand financial emergencies.
What Happens When Parents Have Nothing to Leave?
The absence of an inheritance does not mean a family failed.
Millions of Americans rent because homeownership is unaffordable, unsuitable for their circumstances, or simply not their preferred financial choice.
Renters can also build wealth through savings, retirement accounts, investments, and business ownership.
Nevertheless, families with limited assets may face additional financial responsibilities as parents age.
Adult children may need to help cover housing costs, medical expenses, or other necessities.
Instead of receiving financial assistance from an older generation, they may find themselves providing it.
This reality complicates the popular narrative that an enormous wealth transfer will automatically make younger Americans richer.
For some families, the transfer may be substantial.
For others, there may be little wealth to transfer at all.
America Needs an Ownership Strategy Before the Divide Widens
Preventing inherited housing wealth from becoming an increasingly powerful economic dividing line will require more than encouraging young people to save money.
Policymakers should expand affordable housing construction, improve access to responsible mortgage lending, and consider targeted assistance for first-generation homebuyers.
Programs helping lower-income homeowners preserve and transfer property could also make a meaningful difference.
Estate planning assistance, protection against predatory property purchases, and education about heirs’ property are particularly important for families attempting to retain inherited homes.
For Black American communities, policies addressing historical barriers to property ownership deserve serious consideration.
The objective should not be to punish families that successfully accumulated housing wealth.
It should be to ensure that families without inherited assets still have realistic opportunities to build wealth of their own.
America’s Next Class System Could Be Written in Property Deeds
The coming inheritance divide challenges one of America’s most cherished economic assumptions: that hard work and personal responsibility are enough to guarantee upward mobility.
Increasingly, financial opportunity may depend on decisions made by previous generations.
A young adult inheriting a paid-off house could begin life with a financial advantage that another worker might spend decades trying to achieve.
Neither individual’s work ethic necessarily explains the difference.
America risks becoming a country where one generation inherits the American dream while another spends its entire life renting it.
And unless housing policy expands genuine opportunities for ownership, the greatest wealth transfer in American history could also become one of its greatest engines of inequality.
—Michael Lyles, B1Daily


Leave a Reply